What Is Double Materiality and Why It Is So Important
    CSRDMaterialitySustainabilityFeatures

    What Is Double Materiality and Why It Is So Important

    The concept of double materiality refers to the analysis, evaluation and impact that ESG (Environmental, Social, Governance) objectives can have on a company's financial performance and the impact on social and environmental issues, in terms of external materiality.

    Read the article
    12/10/2024Of 3Bee, Angelina Tortora
    269 Views
    12/10/2024Of 3Bee, Angelina Tortora
    269 Views

    CSRD and double materiality

    Disclaimer: this is an automated translation from Italian. Go to the original article.

    The issue of dual materiality is only one aspect of the broader topic of the latest sustainability reporting directive (CSRD). This concept, which has its roots in the financial world, has emerged in the context of corporate reporting and concerns the inclusion of information necessary to influence the decisions of those reviewing the annual report. Materiality, therefore, is not a new idea, but reflects a fundamental principle: providing information that can guide economic and financial decisions related to sustainability with the integration of ESG objectives into corporate policies.
    CSRD e doppia materialità

    Double materiality and the involvement of supply chain

    The origin of the concept of materiality, through regulatory influence, does not only affect large companies, but extends to the entire supply chain over time. It is crucial to consider how those who can influence, and are influenced by our organisation, are mappable. This mapping is an issue already addressed in several sustainability standards (including the ESRS E4 Biodiversity and Ecosystems standard and GRI 101 biodiversity) that have sought to define how to identify and involve all relevant actors, from suppliers to employees to civil society. It is crucial to understand how these actors can influence the organisation and vice versa. This involvement is essential, just as it is important to consider how we can listen to their voices.

    Doppia materialità e il coinvolgimento di tutta la filiera
    XNatura

    Information and transparency in sustainability reporting

    Materiality is based on the principle of inclusion of certain corporate information. We speak of corporate records, which implies a broad reflection on what this really means. First of all, it is necessary to recognise the importance of information in relation to a specific context. This is not an objective importance, but rather one that varies according to the company and its environment. In addition, it is important to meet the needs and expectations expressed by our stakeholders. Companies must listen to these voices in order to understand what the emerging demands and expectations are. Finally, the issue of transparency is crucial: materiality must always be linked to transparency, as sustainability also serves as a communication tool. In sustainability reports, it is important to select information so that it is relevant and useful to the reader.

    Informazione e trasparenza nel report di sostenibilità

    Concept of double materiality

    The CSRD directive devotes ample space to this topic, which, although not new, is now being addressed with greater attention. The distinguishing feature of double materiality is that it considers two perspectives: impact materiality, which focuses on the company's internal impacts, and stakeholder materiality, which examines how the company's actions can influence the outside world. These two aspects are interconnected and represent a significant shift in the way materiality is conceived. It is crucial to consider these perspectives together to fully understand the impact of actions and to report effectively. As explained by Dr. Sara Moggi (Associate Professor in Business Administration at the University of Verona) in 3bee's webinar, the concept of materiality is already present in current business practices, as highlighted by the 2019 Carbon Discloure Project climate report.

    Concetto di doppia materialità
    XNatura

    Double materiality and 2 aspects: substantive and financial

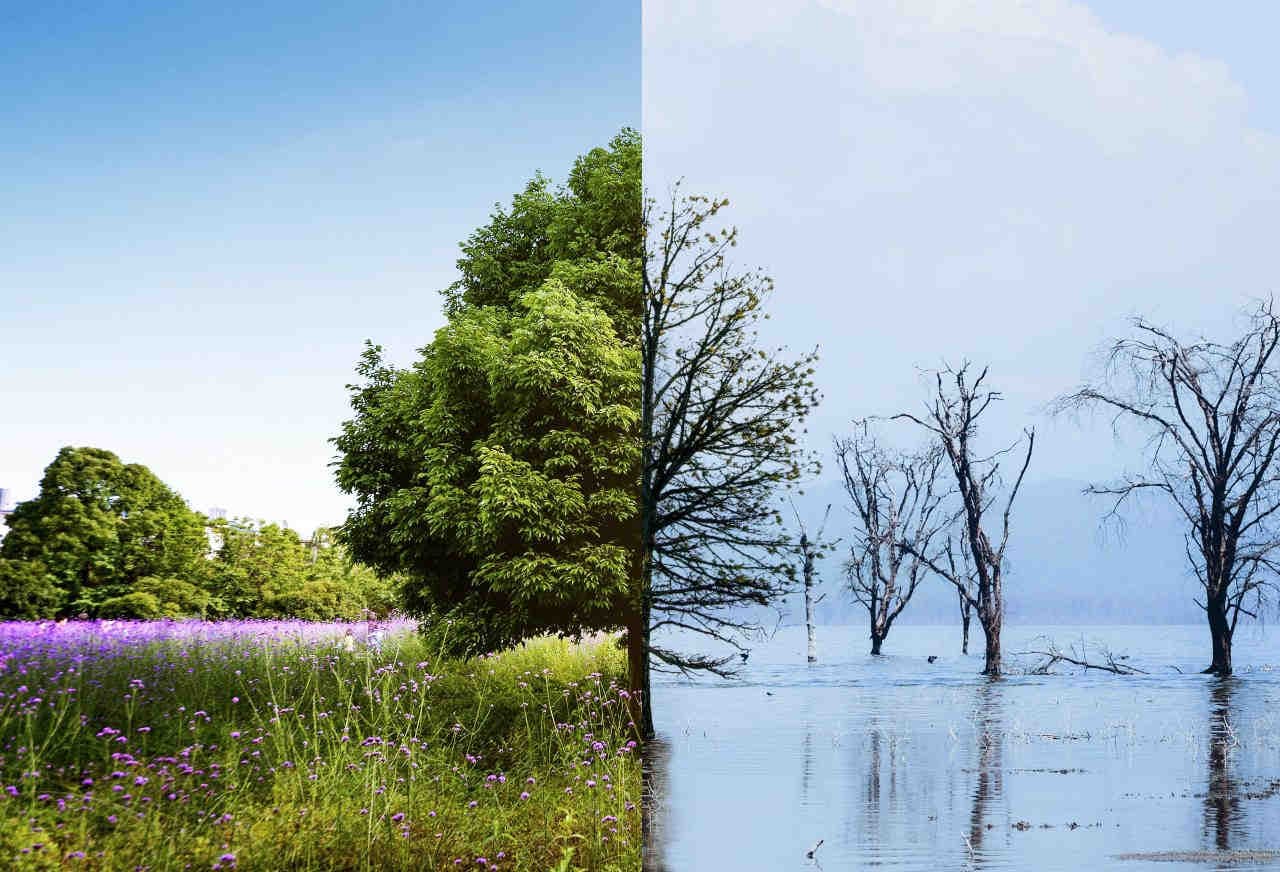
    Double materiality is based on two main aspects. The first 'substantial materiality' deals with how the company affects the climate and, consequently, its stakeholders, which include customers, employees, investors and civil society. Impacts are not static, but dynamic, including both already measurable and potential effects. The "financial materiality", assesses how climate change may affect a company's financial performance. These days, we observe how climate change is impacting corporate performance, particularly liquidity and financing opportunities. Investors, in this context, are a key audience. Sustainability considerations are an integral part of sustainable finance to support the European Green Deal.

    Doppia materialità e 2 aspetti: sostanziale e finanziario
    3Bee

    Risks of climate change: Impact materiality and TCFD

    It is crucial to consider that environmental and social impacts can also influence financial materiality. In this context, impact materiality plays a key role: it is necessary to analyse how external effects can affect internal performance. The two dimensions (materiality materiality and financial) are not separate, but interconnected. Climate change continues to transform our assessment of materiality, as evidenced by the recent update of the TCFD document, which considers various aspects and regulatory pressures. The Task Force on Climate-related Financial Disclosures (TCFD), established in 2015 by the Financial Stability Board (FSB) to develop recommendations on climate risk reporting. Led by Michael R. Bloomberg and composed of 32 experts, the TCFD aims to assess the risks of climate change to global financial stability.

    Rischi dei cambiamenti climatici: Impact materiality e TCFD

    Materiality Implementation Process

    The process of implementation of materiality is complex and articulated. The document of the Implementation Guide published on 2 February presents four phases, of which the first three are in fact circular, emphasising the dynamism of the process. The phases are divided as follows: 1. Exploring & Preparing; 2. Planning & Resourcing; 3. Implementing & operationalising 4. Full implementation These relationships obviously have impacts, risks and opportunities. They are strongly influenced by both the services offered by the company and the geographical distribution of its facilities or operations. In addition, there is a lot of contextual information to consider, such as the current geopolitical situation, which is certainly relevant. It is crucial to identify the stakeholders to be involved in this process.

    Processo di implementazione della materialità

    The first phase: exploration and preparation

    The first phase is exploratory and focuses on fundamental questions, involving the selection, design and development of the intervention to be implemented. Activities in this phase include: 1.Needs assessment and evidence to support the intervention 2. Analysis of suitability, feasibility and appropriateness 3. Implementation readiness assessment 4. Development of necessary leadership 5. Stakeholder engagement planning 6. Selection or design of the intervention 7. Identification of expected results 8. Development of a theory of change and a logic model

    La prima fase: esplorazione e preparazione

    The second phase: planning and resources

    The second phase is the identification of impacts, which may be actual or potential, and should be analysed in terms of risks and opportunities. Two approaches can be adopted at this stage: 'top-down' or 'bottom-up'. In the materiality assessment document, reference is made to the possibility of using the annexes of the first EFRAG standard to identify material areas. In fact, within the first general standard, there is a useful list for this identification phase. A more advanced approach is one in which the company independently identifies the areas to be considered in the context of materiality. This can start with a 'top-down' approach and then develop into a more 'bottom-up' approach. The assessment phase is probably the most complex to implement, but it is essential to understand and weigh up the aspects and impacts.

    La seconda fase: pianificazione e risorse

    The third phase: implementation and operation

    In this third phase, the intervention is implemented for the first time, initially on a pilot basis before full implementation. Although expectations may be high, actual implementation often tends to take longer than expected. It is crucial to manage stakeholders' expectations to prevent them from becoming discouraged. The implementation plan drawn up in phase 2 should guide activities. It is important that it is widely shared, especially with those who are responsible for its implementation, monitoring and evaluation. In addition, the plan should be regularly reviewed and updated to adapt to changing contexts and circumstances.

    La terza fase: implementazione e operatività

    Phase four: full implementation

    In this last phase, the intervention is fully operational and well integrated in the context. It is used consistently, supported by appropriate structures and resources. The results of the intervention are now ready to be evaluated, providing the opportunity to demonstrate impact and promote improvements through continuous learning cycles. Those involved in implementation should also reflect on the process and learn from the experience. This learning can be valuable to guide future decisions regarding the implementation of other interventions.

    Quarta fase: implementazione completa

    Financial impact and materiality are 2 related concepts

    Of relevance is the relationship between financial impact and materiality. These two aspects are often represented as circles or Venn diagrams. However, it is essential to remember that, as indicated by the EFRAG, they must be considered together. It is crucial to understand how material and financial impacts are related and that one does not exclude the other. In this context, the XNatura Platform, by 3Bee Ecosystem makes it possible to identify and close the nature, climate and biodiversity gaps of companies, municipalities and natural parks, by quickly and easily monitoring four key risk indices in line with international standards and identifying a real climate and biodiversity strategy, based on the impacts detected and the dependencies on the ecosystem services directly involved.

    Impatto finanziario e materialità sono 2 concetti correlati
    12/10/2024Of 3Bee, Angelina Tortora
    269 Views
    Newsletter
    newsletter
    Subscribe to the Blog about bees and biodiversity

    Frequently Asked Questions

    Do you have any doubts or other curiosities about this article? Here you will find some insights